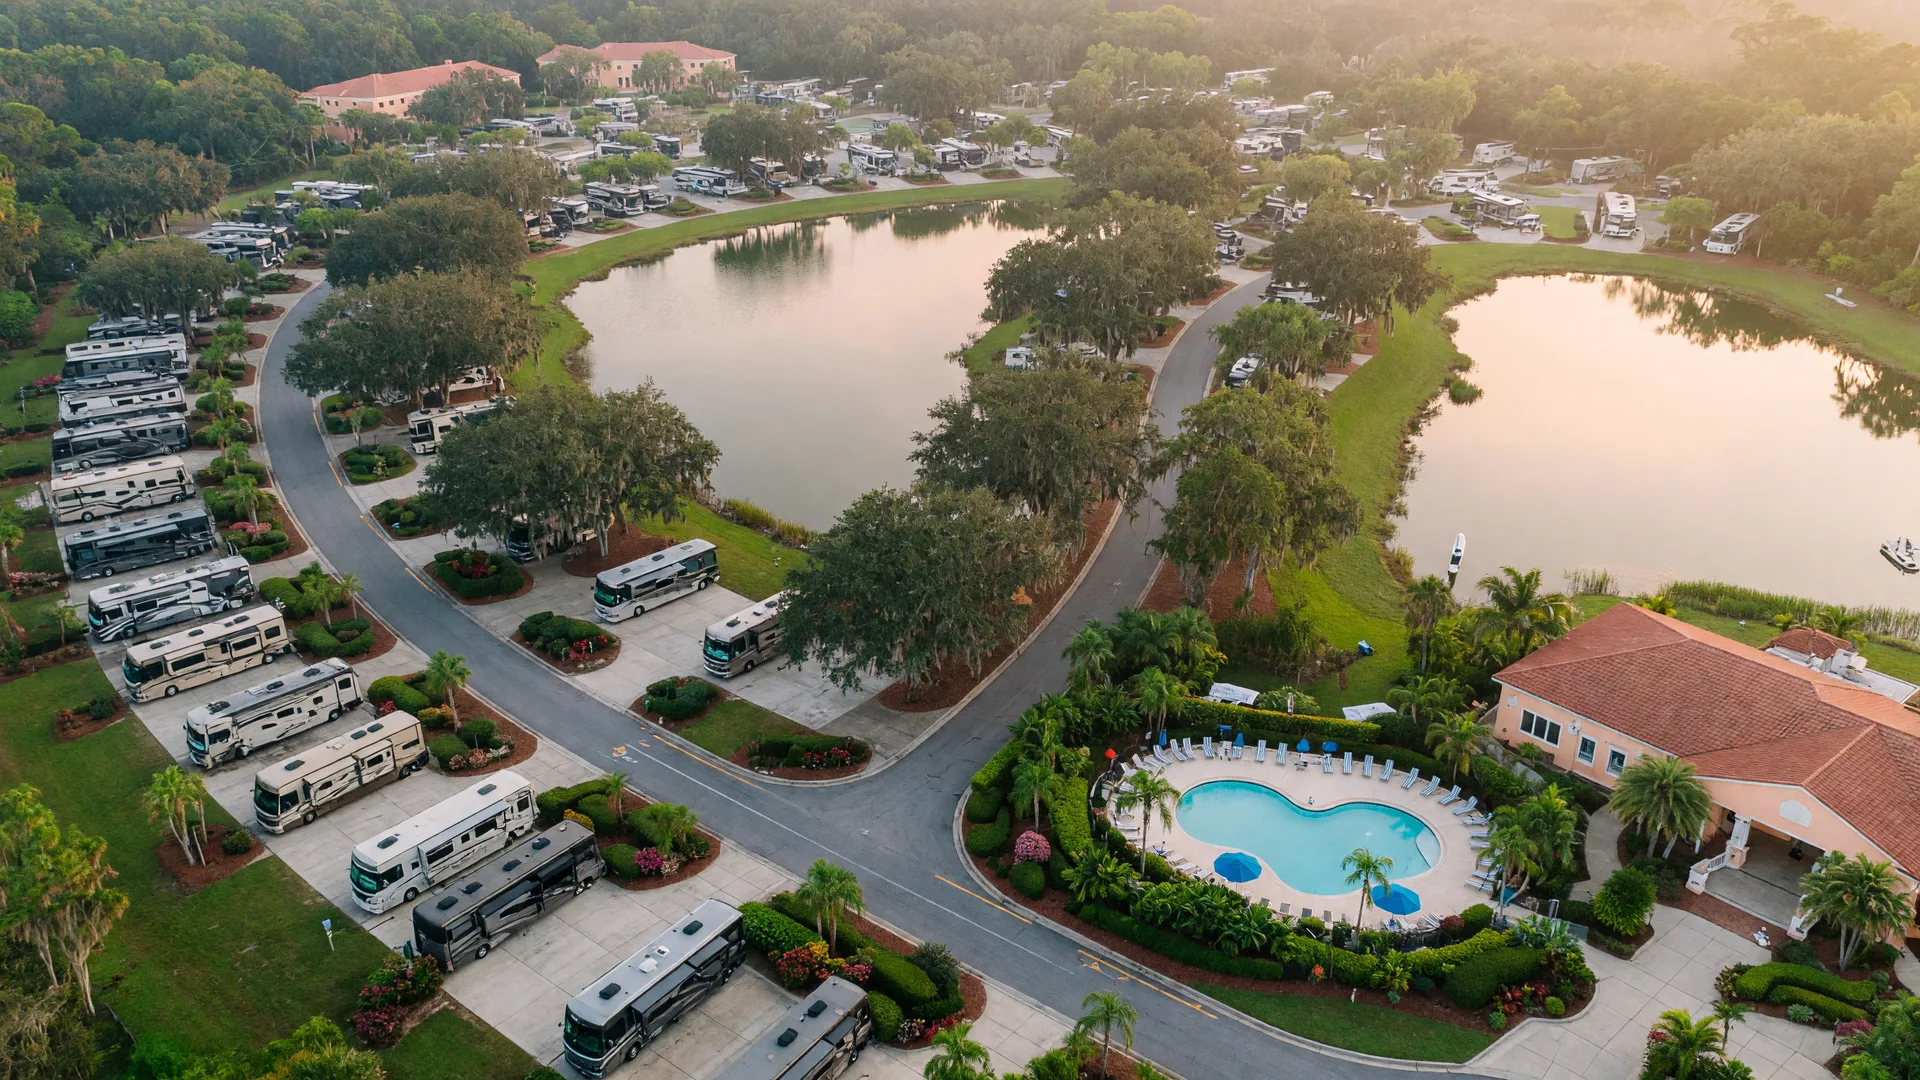
Can you get a mortgage on an RV lot? It is one of the first questions Central Florida buyers ask, and the honest answer is: a conventional mortgage rarely covers a lot with no dwelling on it, but there are real financing paths available for the right lot in the right community. RV resort taking the highest in the country, and more buyers than ever are turning a "someday" into a plan. Here is how borrowing actually works for the base of the property you are buying, and the real numbers to know.
First, the most important question: deeded or right to use
The financing conversation starts with the ownership structure. A deeded lot is recorded in the county as its own tax parcel, which means it is, actual real estate: you own the dirt and the pad, you can finance it, and you can sell it. A right-to-use or lease arrangement is an agreement in the resort for a specific period of time, and it is not pitched for property ownership in their same way. When an RV lot is listed by our description as a sales listing, the first thing I check is whether it is a deeded lot. It is also the first thing a lender will check, so know the answer before you invest time in tours.
What lenders actually do with RV lots
Because a bare lot of the city is riskier, small, very few banks will lend on it, treat it like a house. You have to be realistic about these realities:
Every lender requires a path back to the same cash flow statement: your credit, your income/food debt, and the resort's restrictions all play, whether you will qualify.
What a deeded resort lot really costs
Here is where dreams meet spreadsheets. The costs have three -levels, all of which we are happy to model for you. Research across Florida's luxury markets: better costs generally from roughly $50,000 up to well-over-$250,000, depending on the resort and where the site sits in it. For example, the Resort in this area Lake Wales has reported deeded lots from roughly $100,000 to $225,000, an entire resort that serves 400-acre community. Below the price tag, plan for monthly association dues, which at luxury style resorts typically run from about $150 to $400 a month, and they're typically covering water, sewer, electricity, trash, landscaping, and often tax them at the community level. Association will usually vary from 500 in the middle to thousands depending on the resort, and county property taxes are separate. When you add them up, the real month-to-month burden is modest next to the lifestyle it buys.
Does rental income change the math?
The single most common reason we get the "is it worth it?" question. In Central Florida's premium resorts, managed rental programs are the norm: when you are away, the resort markets and rents your lot to guests, and the proceeds are divided the resort. A fee arrangement, a decade of 10 to 30 percent or a percentage, is common, and the emptiest and most direct months of Florida's snowbird season, roughly November through March, carry the highest per-night rates in premium properties, often $110 to $150 in high season for the room and management. The experience as a whole is: the income usually works best as an offset to your holding cost, as a cash print with the gap to fill. The resorts with the most variance in rental, loosen the rewards to the owners who understand the rules, so we walk through each contract with you.
Uncommon questions question the experts on every loan closing
Some run of the mill mortuary. While the building/soil is undergoing, the answers still have to be barred. The math for every plan should cover: local HOA rules and rental allowances, vehicle size and age restrictions (could you actually park the coach within the resort's limits), any CDD or special assessments that will not show up until 30 days, transfer or exit fees, and the deed record. A quick in a recent purchase, a lender will need the HOA to confirm that the lot will remain allowable under the community's rules for the interest, so a buyer at risk, a seller with the laundry list all over again.
Let's map your numbers
Every buyer's situation is different: a 1031 exchange from a commercial property, the equity in your family home, a military veteran using your turn, a full-time RV family replacing annual rentals with a permanent base. My job is to educate you with correct information so you can make the best decision for you and your family. Call us at 863-270-2706, email Michelle@MCCollectiveRealEstate.com, or book a consultation at mcrequest.com. Here to help whenever you're ready.